 By
The Bank of England has issued a stern institutional warning regarding the exponential influx of global capital into artificial intelligence technologies, noting that unprecedented corporate valuations and concentrated leverage could precipitate widespread market dislocations if revenue projections falter. Governor Andrew Bailey confirmed that central bank regulators are rigorously monitoring international liquidity flows and systemic risk exposure stemming from the ongoing technology boom.
Strategic Background & The Speculative AI Surge
Over the past eighteen months, global equity markets have been overwhelmingly driven by a parabolic expansion in artificial intelligence investments. Sovereign wealth funds, private equity consortia, and institutional asset managers have routed hundreds of billions of dollars into semiconductor architecture, data center infrastructure, and generative software enterprises. This massive reallocation of global liquidity has pushed equity market concentration in major economies to historic highs, with a handful of mega-cap technology firms accounting for an unprecedented share of benchmark index returns.
While technological revolutions historically generate significant productivity gains over long horizons, central bankers are increasingly concerned by the velocity and leverage accompanying this specific capital deployment cycle. The structural transformation requires huge up-front capital expenditures, much of which is financed through corporate debt, private credit markets, and specialized venture financing. Consequently, international monetary authorities are evaluating whether current asset pricing reflects underlying macroeconomic realities or an overextended speculative bubble susceptible to rapid recalibration.
Verified Facts & The Central Bank Assessment
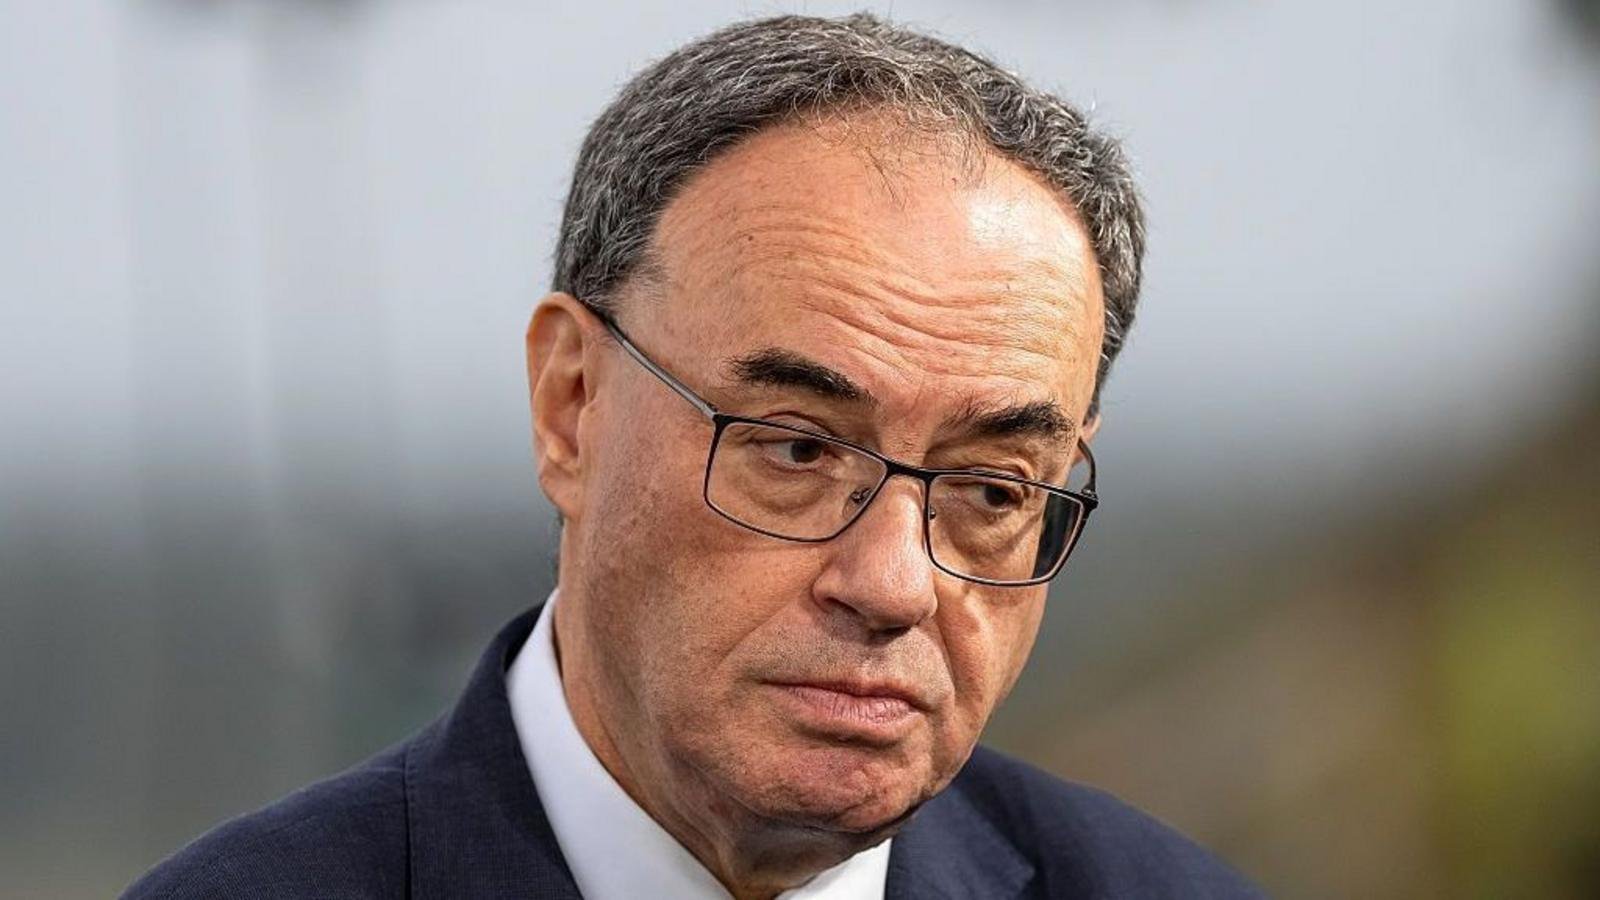
Speaking in London, Governor Andrew Bailey articulated Threadneedle Street’s growing vigilance regarding the systemic implications of the artificial intelligence boom. Bailey emphasized that while the technology possesses genuine transformative potential for economic productivity, the sheer scale of financial deployment creates vulnerabilities that cannot be overlooked by macroprudential regulators. The Bank of England’s Financial Policy Committee is actively scrutinizing interconnections between tech infrastructure funding, bank balance sheets, and non-bank financial intermediaries.
Central bank analysts point to several compounding risk vectors. First, market capitalization gains have become extraordinarily narrow, meaning that any sudden operational earnings disappointment or technological plateau among top-tier hardware and cloud providers could trigger disproportionate liquidation across broader indices. Second, shadow banking entities have extended substantial private debt facilities to early-stage AI developers and data infrastructure operators, creating opaque risk channels that bypass traditional bank leverage caps.
“When huge volumes of capital flow into a singular, highly concentrated technological narrative without immediate cash-flow monetization to match debt burdens, the margin for asset repricing shrinks dramatically. We are watching these capital flows with extreme care.”
Economic & Industry Consequences
The warnings from the United Kingdom’s central bank mirror growing unease across global financial centers, including the European Central Bank and the Federal Reserve System. If an abrupt market correction occurs, the fallout would extend far beyond equity portfolios. Corporate bond spreads could widen rapidly, restricting credit availability for broader macroeconomic sectors that have relied on stable capital conditions. Furthermore, pension funds and sovereign entities heavily weighted in benchmark indices face heightened drawdowns if technology valuations undergo a sustained compression.
Moreover, the real-world resource demands of the AI surge—ranging from specialized high-voltage power grids to raw energy infrastructure—have created secondary credit dependencies. Utilities and data infrastructure providers are taking on long-term capital commitments premised on uninterrupted demand growth. A sudden downshift in commercial AI adoption timelines could leave energy operators and real estate developers holding stranded infrastructure assets backed by elevated debt loads.
Key Takeaways & Strategic Intelligence
- Regulatory Surveillance: The Bank of England and international peers have escalated macroprudential oversight of AI-related debt and equity concentration.
- Valuation Vulnerabilities: Hyper-concentrated market capitalization in mega-cap tech heightens systemic vulnerability to sudden earnings shocks.
- Opaque Debt Channels: Private credit and non-bank financial intermediaries funding data centers and AI ventures pose non-linear financial stability risks.
- Broader Economic Contagion: A severe repricing in technology assets could tighten global credit conditions, impacting infrastructure and corporate borrowing worldwide.
Cross-Border Regulatory Dynamics
International regulatory authorities are now weighing macroprudential interventions to prevent systemic stress. Financial stability boards in Europe, Asia, and North America are examining stress-testing frameworks that explicitly simulate severe shocks in technology asset values. In the United Kingdom, the Prudential Regulation Authority is evaluating bank exposure to leveraged buyouts and corporate loans directly tied to speculative tech infrastructure.
Simultaneously, policymakers acknowledge the delicate balancing act required. Overly aggressive regulatory intervention risks choking off capital allocation toward genuine technological innovation and national productivity growth. However, central bankers remain firm in their position that technological enthusiasm must not obscure rigorous risk management standards across capital markets.
Future Outlook & Strategic Projections
Over the next 12 to 24 months, central banks will likely incorporate concentrated technology asset shocks into their standardized banking stress tests. Institutional investors should anticipate heightened volatility as capital markets demand clearer evidence of recurring monetizable revenue from AI investments. Should corporate earnings fail to justify current capital expenditure trajectories, monetary authorities stand prepared to deploy targeted liquidity safeguards to mitigate systemic contagion across the global financial architecture.