 By
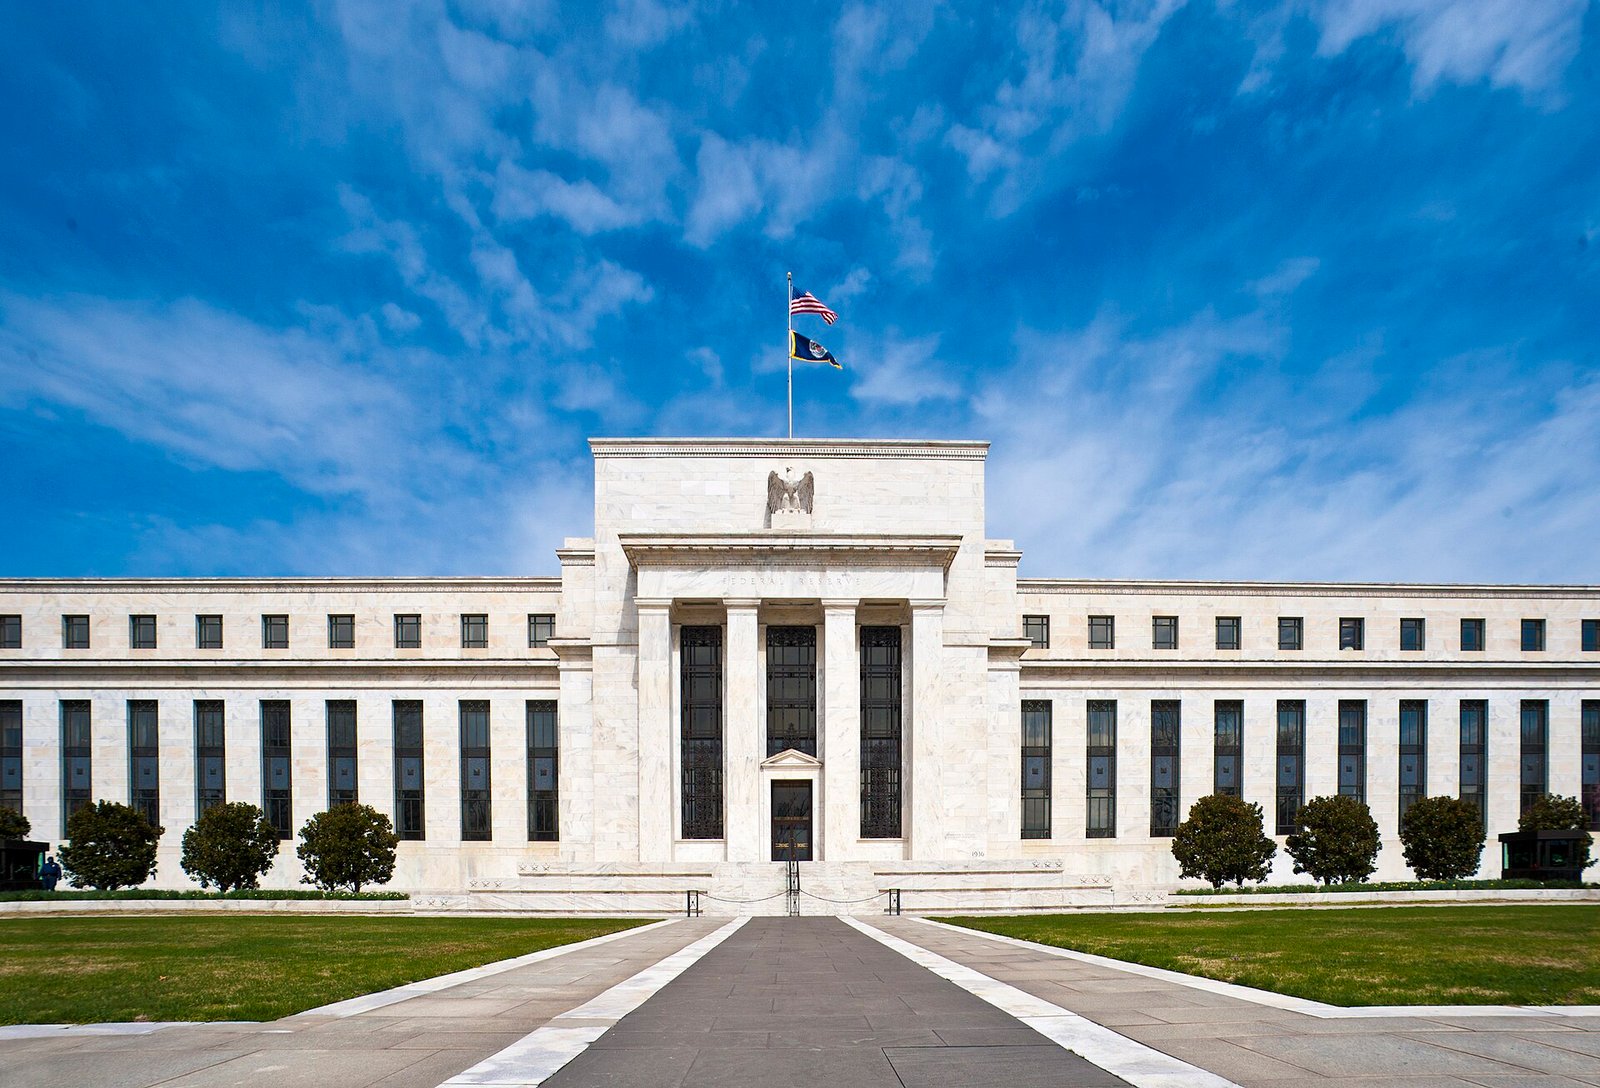
Minutes of the Federal Reserve’s October meeting show the decision to hold rates was a far closer call than the official 10–2 vote suggested — with almost all officials expecting further hikes, and Governor Christopher Waller floating a move twice the usual size.
By The BNN Media
The Best News Network
News Beyond the Borders
WASHINGTON, United States — Minutes of the Federal Reserve’s October meeting, released on Wednesday, 18 November, showed the rate hold was a much closer call than the official 10–2 vote suggested. Almost all officials anticipated further rate hikes ahead, and a few were open to a move bigger than 25 basis points in December should inflation data disappoint — with Fed Governor Christopher Waller floating a 50-basis-point move. A 25-basis-point hike on 9 December is now about 95 percent priced in by markets, and the 10-year US Treasury yield is holding above 5 percent.
A Closer Call Than the Vote Suggested
The headline vote in October was 10–2 in favour of holding rates. The minutes tell a different story. Officials saw mounting evidence of persistent inflation, and the discussion was far more divided than the tally implied. The release landed in a market already nervous about sticky prices, and it removed any lingering doubt that the Fed’s next move is up, not down.
The shift matters because it reframes the whole autumn. For months, investors had treated the October hold as a pause before cuts. The minutes show it was, in the view of almost all officials, a pause before further tightening. The question is no longer whether the Fed will hike again, but by how much — and how soon.
The 10–2 vote was the official record. The minutes are the real one — and they show a central bank that came much closer to raising rates in October than anyone knew at the time.
Waller’s 50-Basis-Point Gambit
The most striking detail in the minutes is the intervention of Fed Governor Christopher Waller, who floated a 50-basis-point move — double the standard quarter-point step. A few officials were open to a move bigger than 25 basis points in December should inflation data disappoint, and Waller’s name is the one attached to the half-point idea.
A 50-basis-point hike would be a blunt instrument. It would signal that the Fed believes inflation is not merely sticky but re-accelerating, and it would hit borrowing costs across the economy at once — mortgages, corporate debt, credit cards. That it was even discussed, by a sitting governor, tells markets the Fed’s patience is wearing thin.
For now, the market’s base case remains a 25-basis-point hike on 9 December, about 95 percent priced in. But the minutes have put the larger move on the table as a live possibility, and traders will now read every inflation print between now and December as a vote for or against it.
Markets: Stocks Slide, the Dollar Climbs
Wall Street took the news badly. The S&P 500 fell 0.23 percent to 7,323.63 — its fifth straight loss — and the Dow Jones dropped 1.11 percent to 50,198.20. The tech-heavy Nasdaq managed a modest 0.42 percent gain to 24,429.89, ending a four-day slide, but the broader mood was defensive. The VIX, Wall Street’s fear gauge, stood at 24.6.
The bond market told the same story. The US 10-year Treasury yield eased slightly to 5.07 percent, still above the 5 percent line that has become the market’s dividing line between normal and alarming. The dollar index rose 0.41 percent to 103.92, near a 19-month high, with the euro sliding to 1.0967 and the pound to 1.3135.
Sector moves showed investors rotating hard:
- Cybersecurity rallied, with Palo Alto Networks up about 10 percent and CrowdStrike up about 8 percent.
- Target gained about 4 percent on strong quarterly sales, ahead of Walmart’s earnings.
- Managed health insurers fell sharply, with UnitedHealth down about 10 percent and Humana down about 13 percent.
- Miners dropped, with Freeport-McMoRan and Newmont down more than 6 percent as commodity prices slid.
- Nvidia erased initial post-earnings gains to finish down 2.9 percent, amid continuing uncertainty after co-founder Jensen Huang’s departure, and Moody’s cut its outlook after the exit.
The market’s message is consistent across stocks, bonds and currencies: borrowing costs will stay higher for longer, and the easy money of the past decade is not coming back.
Commodities and Crypto Feel the Squeeze
Commodities bore the brunt of the session’s liquidation. Crude oil dropped 4.56 percent to $82.09 a barrel, and gold shed 3.58 percent to $3,725.90, near a 14-month low, as investors ditched inflation hedges in favour of cash yields. Silver fell to around $45.30, and copper hit a seven-month low, down 3.50 percent to $12,770 a tonne on slowing Chinese demand.
Bitcoin slipped 2.18 percent to $63,478.72, with Ether down 1.29 percent to $1,799.37, Solana off 0.66 percent to $74.61, XRP down 0.81 percent to $0.975 and BNB falling 1.60 percent to $586.48. The crypto slide came as the Ledger hardware wallet tampering investigation spread to Berlin, adding a security scare to the rate-driven sell-off.
Europe and Asia followed the same pattern. The STOXX 600 slid 1.03 percent to 644.05, its third consecutive loss, and London’s FTSE 100 fell 1.3 percent. In Asia, the Hang Seng dropped 2.11 percent to 22,803, Taiwan fell 4.60 percent to 38,348, and the ASX 200 lost 1.04 percent to 8,730, while the Nikkei rose 0.46 percent to 59,298 and India’s Nifty added 0.33 percent to 25,312.
Gulf tensions added a further complication: a tanker was hit near Hormuz and Washington is reportedly weighing new strikes on Iran. Even so, oil was flat to lower and gold kept falling, as rate fears outweighed the safe-haven bid.
What to Watch Next
The calendar between now and the Fed’s 9 December meeting is crowded, and every release will be read as evidence for a 25- or 50-basis-point move:
- US jobless claims and the Philly Fed index, due at 13:30 GMT on Thursday, will be the first test of the labour market since the minutes landed.
- Walmart’s earnings will show whether the American consumer is still spending through higher borrowing costs.
- Anthropic’s Nasdaq debut — priced at $83 a share, above its $70–$78 marketed range — will test appetite for the year’s most-watched listing against a backdrop of rising rates.
- US November employment data and upcoming Fed speeches will confirm whether a December hike is fully priced into bonds.
The European Central Bank’s semi-annual Financial Stability Review, released on 18 November, added to the gloom, warning that stretched AI valuations — backed by over $4 trillion in off-balance-sheet debt commitments among big technology firms — carry parallels to the dotcom and subprime bubbles.
The December hike has not happened — it is priced in and expected, not done. But after these minutes, the only serious debate left is whether it will be 25 basis points or 50, and the answer will come from the inflation data. For borrowers, businesses and investors, the era of cheap money is over, and the Fed has just told the world it means it.
Sources: NordFX; Iboro Finance; Serrari Group.
By The BNN Media
The Best News Network
News Beyond the Borders
2 thoughts on “Fed Minutes Reveal December Rate Hike Was a Near Certainty as Waller Floated a Half-Point Move”